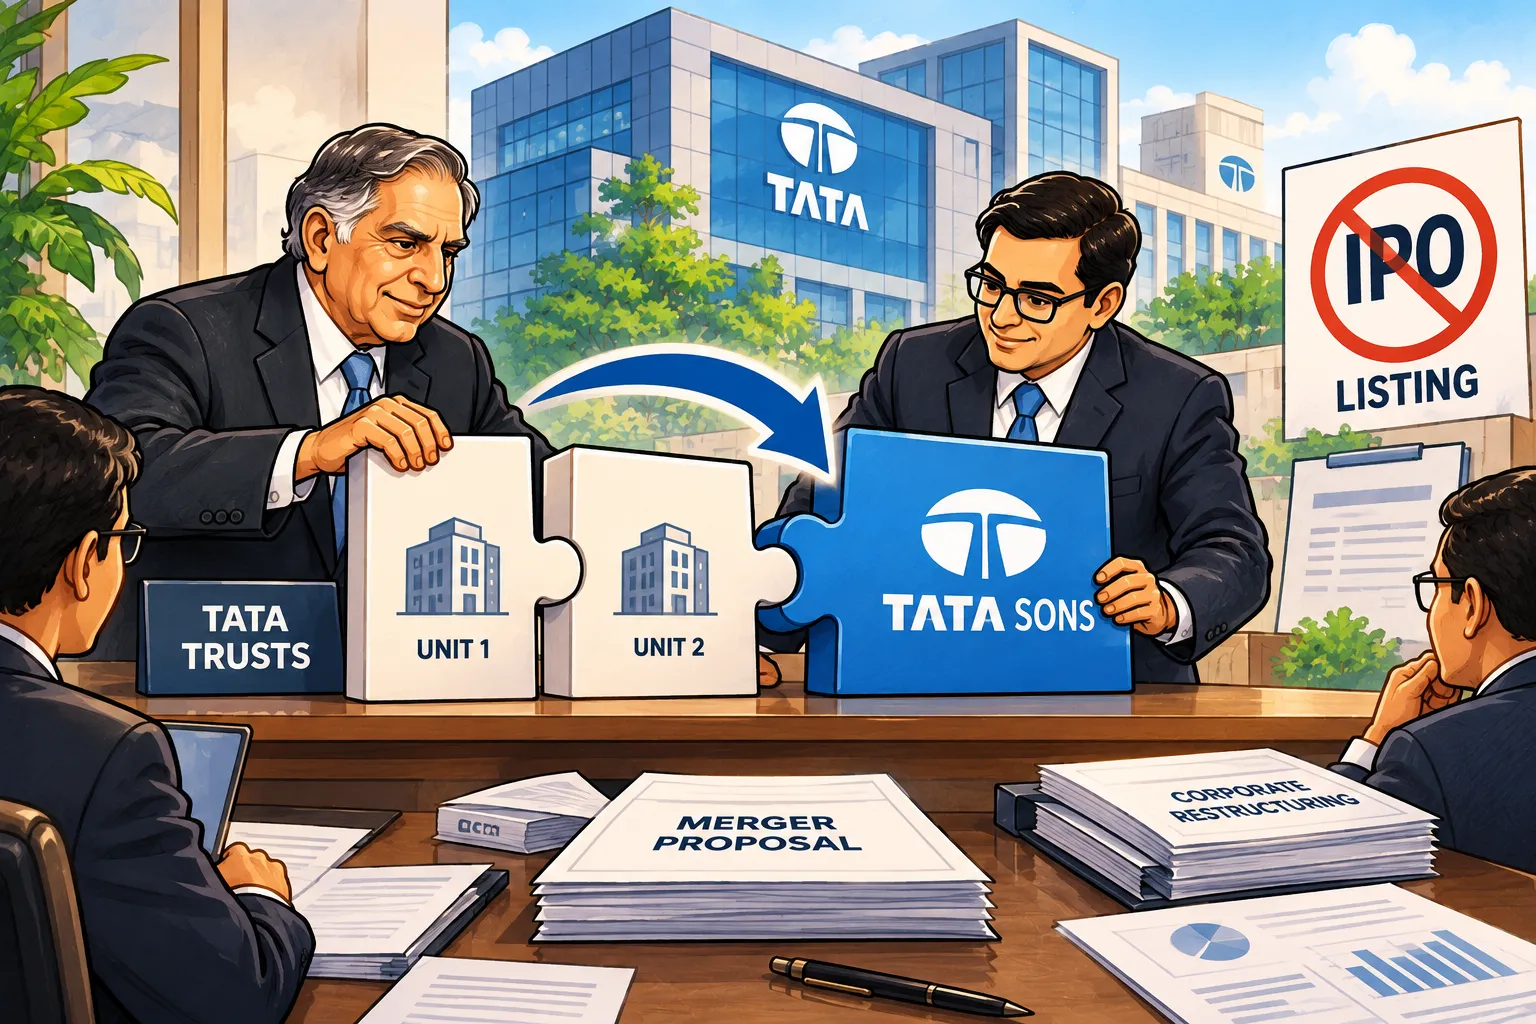
Tata Trusts has proposed merging Tata Electronics Systems Solutions and Tata Consulting Engineers into Tata Sons, arguing the combined entity's operating revenue would place it outside the NBFC and core investment company frameworks entirely, letting Tata Sons stay private after the RBI rejected its earlier bid to avoid listing.
The New Plan
Tata Trusts, Tata Sons' largest shareholder with a 66 per cent stake, announced a strategic reorganisation plan on Monday evening, proposing to revert Tata Sons to its old operating-company model through an amalgamation. Under the plan, Tata Electronics Systems Solutions (TESS), a wholly owned subsidiary of Tata Electronics, and Tata Consulting Engineers (TCE), a private-sector engineering and project consultancy, would merge into Tata Sons Pvt Ltd. Farokh N Subedar, advisor to Tata Trusts and a Tata group veteran who retired as Tata Sons' chief operating officer and company secretary in 2017, briefed reporters on the plan in Mumbai.
Tata Trusts argues the restructuring would give Tata Sons genuine operating revenue and operations of its own, on top of its role as the group's holding company, a structure the trust says characterised Tata Sons for almost 80 of its 100 years, including its ownership of Tata Consultancy Services as an internal division before that business was demerged into a separate subsidiary in 2004.
The Numbers Behind The Argument
Tata Trusts said the merged entity arising from combining TESS and TCE with Tata Sons would generate operating revenue of ₹1.05 trillion, far exceeding its income from financial assets of ₹40,072 crore, which would represent 64.3 per cent of the combined entity's total income. On that basis, Tata Trusts argues the entity would fail to meet the RBI's "principal business criteria" that defines an NBFC, and would also fall outside core investment company (CIC) conditions, which require net assets exceeding ₹2 trillion with group-company investments making up more than 90 per cent of net assets. Tata Sons' standalone assets currently exceed ₹2 trillion.
Tata Trusts has written to the Tata Sons board asking it to consider and approve the proposal, including applying to the RBI for the required no-objection certificate under the RBI's 2025 voluntary amalgamation directions for NBFCs.
The Backdrop: A Board Already Split
The RBI placed Tata Sons on its upper-layer NBFC list in September 2022, giving it three years to list. Tata Sons cleared all its debt in 2024 and applied to voluntarily surrender its CIC status to remain private, but the RBI rejected that application earlier this month, telling the company to comply with listing norms immediately. The Tata Sons board backed listing on September 17, but Noel Tata, a nominee director and Tata Trusts chairman, opposed the move, arguing "considerable room remains" to negotiate rather than concede to listing.
The Shapoorji Pallonji group, Tata Sons' second-largest shareholder with over an 18 per cent stake, supports listing, since it would let the group partially dilute its stake and reduce its debts. Shriram Subramanian, founder and managing director of proxy advisory firm InGovern, told Business Standard it may be difficult for the RBI to accept a restructuring plan at this stage, given it has already rejected Tata Sons' CIC-surrender application once.
Also Read: Essar Group To Invest $15 Billion In Largest-Ever US Steel Plant, In Iowa
Why It Matters
This is a direct, numbers-based counter-proposal to a regulator that has already rejected Tata Sons' first attempt to avoid listing, filed just eleven days after Tata Sons' own board backed listing as the path forward. Whether the RBI accepts a restructuring built specifically to engineer the company outside its NBFC and CIC definitions, rather than accepting the board-endorsed listing route, will determine not just Tata Sons' own structure but also set a precedent for how other large diversified holding companies might attempt to sidestep similar regulatory obligations in the future.