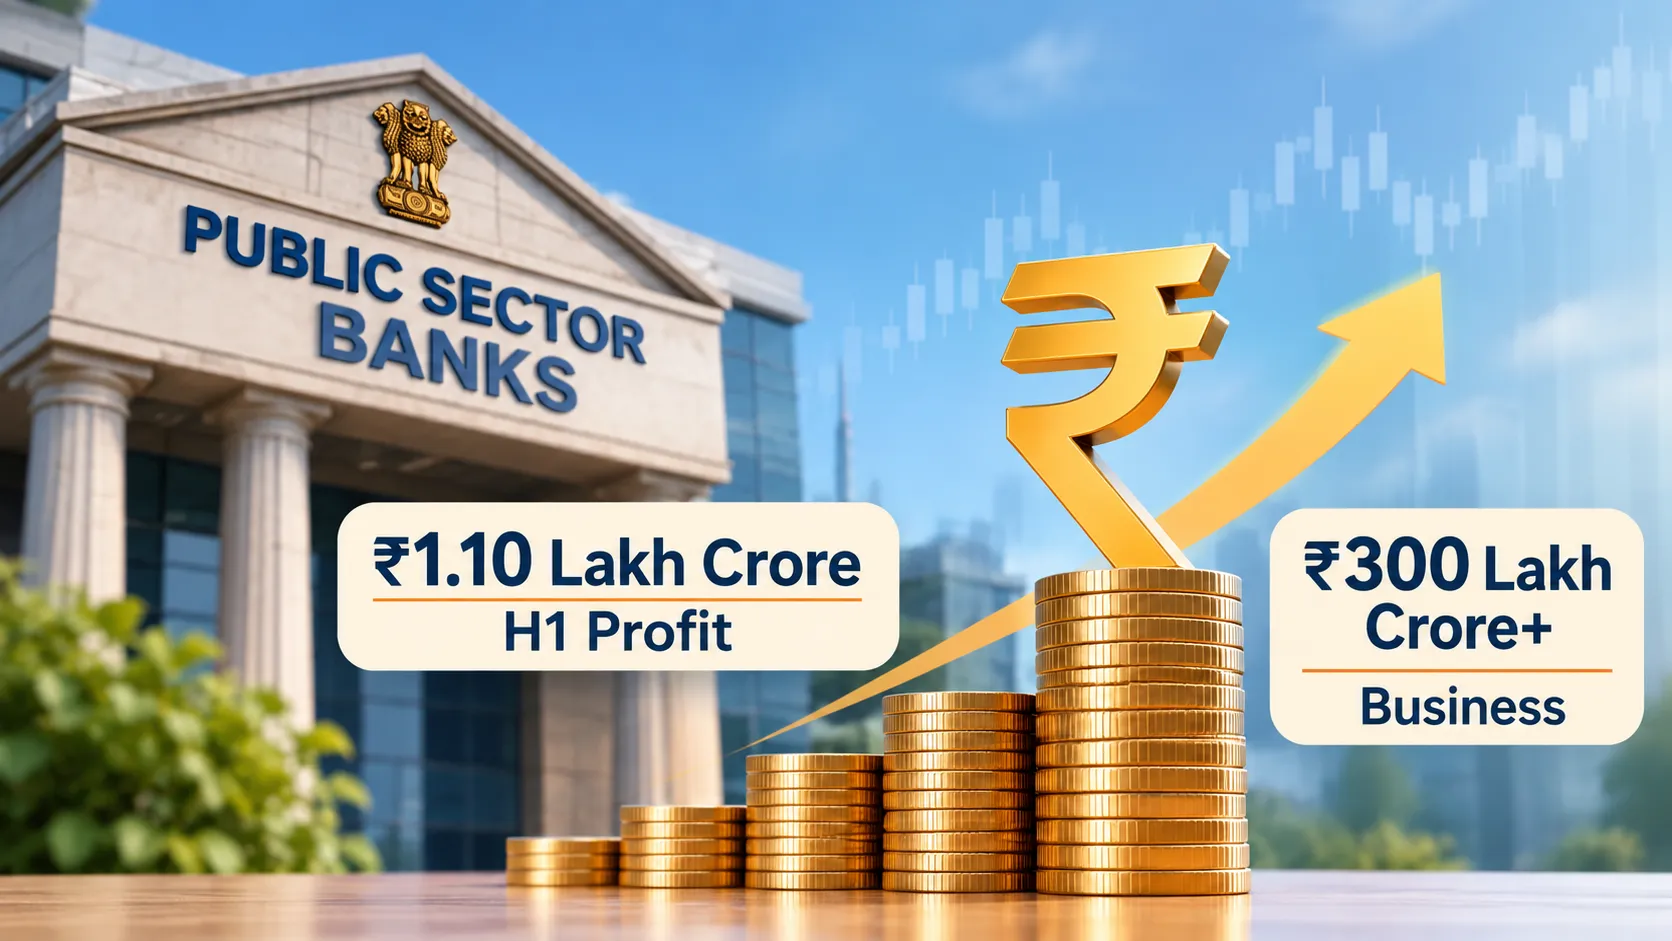
The Finance Ministry said public sector banks earned an aggregate net profit of about ₹1.10 lakh crore in April-September 2026, up 16.9%, while total business crossed ₹300 lakh crore for the first time.
The Headline Numbers
The Ministry of Finance said on Wednesday, November 18, 2026, that the 12 public sector banks (PSBs) reported their highest-ever aggregate net profit in the first half of FY2026-27. Net profit was ₹1,09,540 crore, or about ₹1.10 lakh crore, a rise of 16.9% from a year earlier. Aggregate operating profit rose 13.9% to ₹1.81 lakh crore.
The ministry said profitability has improved for the fifth consecutive year. Return on assets improved by three basis points to 1.11%.
| Measure | H1 FY27 | Change from a year earlier |
| Aggregate net profit | ₹1.10 lakh crore | Up 16.9% |
| Aggregate operating profit | ₹1.81 lakh crore | Up 13.9% |
| Aggregate business | ₹301.6 lakh crore | Up 15.5% |
| Advances | ₹136.4 lakh crore | Up 18.8% |
| Deposits | ₹165.2 lakh crore | Up 13.1% |
Business Crosses ₹300 Lakh Crore
Total business of the public sector banks, which adds deposits and advances, grew 15.5% year on year to ₹301.6 lakh crore as of September 30, 2026. This is the first time the figure has crossed ₹300 lakh crore. At the end of FY26, aggregate business stood at ₹283.3 lakh crore.
Advances grew faster than deposits. Loans rose 18.8% to ₹136.4 lakh crore, while deposits grew 13.1% to ₹165.2 lakh crore. Some published reports gave the deposit figure as ₹275 lakh crore, but that number does not fit with the reported business total, since deposits plus advances add up to ₹301.6 lakh crore only with a deposit figure of about ₹165 lakh crore.
Where Lending Grew
Credit growth was strong across the segments the ministry highlighted:
- Retail loans: Up 17%
- Agriculture loans: Up 19.5%
- Lending to micro, small and medium enterprises (MSMEs): Up 20.4%
The ministry said the growth reflected continued support from public sector banks for entrepreneurship, financial inclusion and economic activity. It added that the numbers show the banks are meeting the demand for credit with better underwriting capabilities, aided by technology and higher governance standards.
Asset Quality at New Lows
Asset quality improved further. The gross non-performing asset (NPA) ratio declined to 1.69% and the net NPA ratio fell to 0.33%. The ministry said low slippages, improved underwriting standards and stronger recoveries contributed to the decline. Fresh slippages stood at 0.62%.
For comparison, at the end of FY26 the gross NPA ratio was about 1.9% and the net NPA ratio was 0.39%, which were then described as the lowest levels recorded. The latest figures are lower still.
All public sector banks now have a provisioning coverage ratio above 90%, according to the ministry. Provisioning coverage shows how much of the bad loans a bank has already set aside money for, so a higher ratio means a larger cushion against losses.
Capital and Efficiency
Capital buffers also strengthened. The capital-to-risk-weighted-assets ratio (CRAR) reached 16.89% as of September 30, an improvement of 93 basis points from a year earlier. The ministry said these levels are comfortably above regulatory requirements, which gives the banks room to support lending and absorb shocks.
Cost efficiency improved too. The cost-to-income ratio declined by 191 basis points to 47.38%, and the cost-to-assets ratio fell by 14 basis points to 1.60%. The ministry attributed this to investments in technology and digital transformation and to better cost management.
How This Compares With FY26
Public sector banks posted a record net profit of ₹1.98 lakh crore in FY26, which was an increase of about 11% over the previous year, marking the fourth consecutive year of profitability. The first-half profit of ₹1.10 lakh crore in FY27 is already more than half of that full-year total, and the growth rate of 16.9% is higher than the 11% growth reported for FY26 as a whole.
The ministry said the sustained improvement across capital adequacy, business growth, low slippages, asset quality and profitability shows a complete turnaround in the functioning of public sector banks.
What Readers Should Note
These figures come from the Finance Ministry’s own release and are aggregates across 12 banks. They do not show how individual banks performed, and the gains differ from bank to bank. The reports reviewed also do not include net interest margins, which many analysts watch closely as rates change.
One feature worth noting is the gap between loan growth and deposit growth. When loans grow at 18.8% and deposits at 13.1%, banks have to raise deposits faster or find other funding to keep expanding credit. That is a point investors usually track when assessing how long a high pace of lending can continue.